 Veteran Owned & Operated
November 12, 2026 · AmpiFire Content
Commercial Trailer Financing: How It Works & Best Options
Key Takeaways
-
Commercial trailer financing matches a business’s credit, cash flow, and trailer use to a lending structure that sets the interest cost, title ownership, and end-of-term outcome.
-
The main options are dealer-arranged business financing, direct equipment loans, equipment leases, rent-to-own agreements, and Small Business Administration (SBA)-backed loans, each suited to different price ranges and paperwork levels.
-
Leases lower the upfront cash needed but don’t automatically build ownership, while loan payments go toward owning the trailer outright by the end of the term.
-
Rent-to-own through C3 Rentals covers trailers priced at $2,500 to $20,000 over 12 to 48 months, accepting lower credit scores at a higher overall cost.
-
Poplar Bluff Trailer’s business financing runs 12 to 84 months on business credit, with applications handled directly by the dealership’s finance team.
How Does Commercial Trailer Financing Work?
Commercial trailer financing works by matching a business's credit profile, cash flow, and intended trailer use to one of several lending structures, each with different approval criteria and repayment mechanics.
The five principal choices are dealer-arranged commercial financing, a business equipment loan, an equipment lease, an eligible rent-to-own agreement, or an SBA-backed loan. Each option determines who holds the title, what happens at the end of the term, and how much documentation the application requires.
Financing can be structured to cover only the trailer's price, or it can extend to eligible taxes, fees, accessories, and delivery charges, depending on the lender's program. The right choice depends less on finding the "best" product overall and more on matching the structure to the trailer's intended use, its purchase price, the business's credit and cash flow, and whether ownership at the end of the term is the actual goal.
Best Commercial Trailer Financing Options
Dealer-Arranged Business Financing
Dealer-arranged financing coordinates the purchase and the loan application through the same transaction, which cuts down on back-and-forth between separate parties. Poplar Bluff Trailer's program approves applicants based on business credit and offers terms from 12 to 84 months, with financing capacity up to $50,000. Buyers can work with the finance team to get pre-approved before visiting the lot, which establishes a budget ahead of time.
Down payment requirements depend on the lender and the applicant's credit approval rather than a fixed dealer policy. The main advantage is convenience: the dealer supplies the equipment and the transaction information in the same process, and buyers can review available repayment terms before committing.

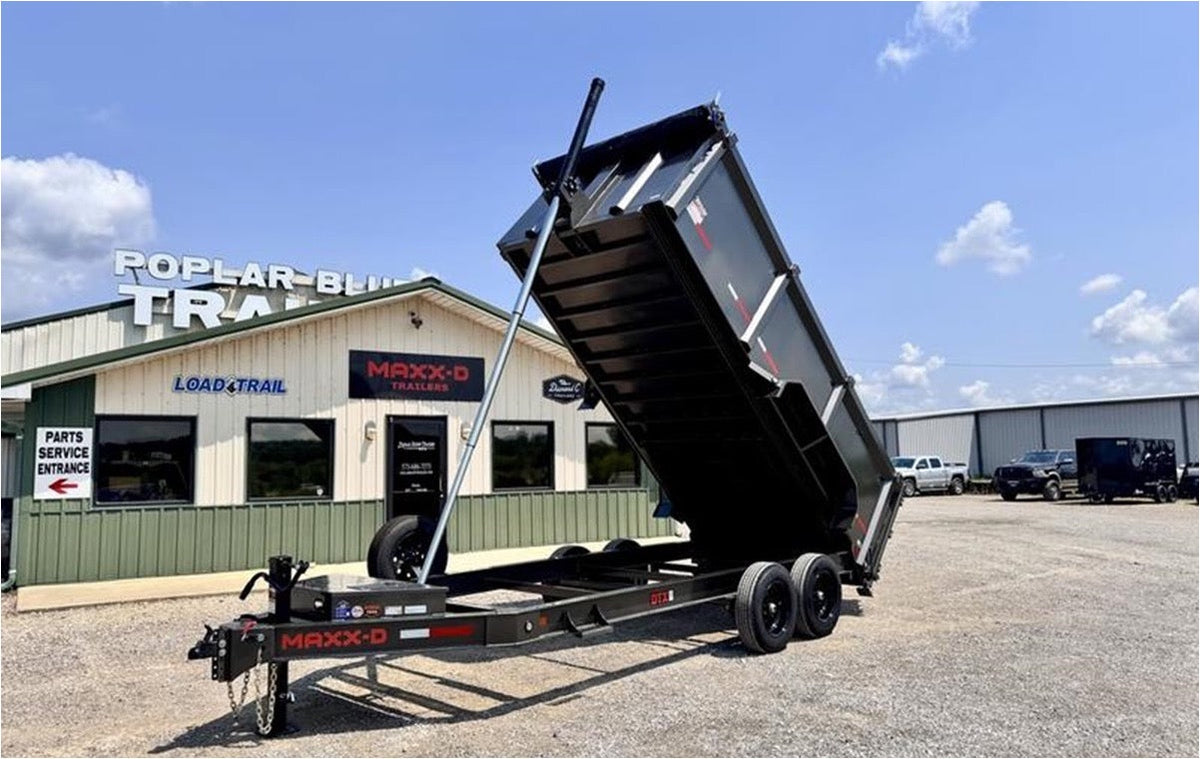
Gooseneck dump trailers often cost more than personal credit financing covers, which makes business financing the natural route.
Direct Business Equipment Loans
Equipment loans work by borrowing funds specifically to purchase an asset, which may then serve as collateral for the loan itself. Banks and equipment-finance companies offer these products for commercial-purpose equipment, including eligible trailers. Because the financing decision is separate from the equipment purchase, this route lets a business compare terms independently against whatever a dealer offers.
The tradeoff is documentation. Minimum loan sizes vary widely between lenders, and some programs are built for larger transactions rather than a single smaller trailer purchase. Banks often ask for tax returns and full financial statements, although some equipment-finance companies offer application-only programs for smaller amounts, so the paperwork depends on the lender and the loan size.
Equipment Leasing
A lease lets a business pay for the use of a trailer over a specified period instead of financing full ownership upfront. Depending on the agreement, the business may return the trailer, renew the lease, or purchase it outright once the term ends. Lower upfront cash requirements and payments spread across the usage period make leasing appealing for businesses that want flexibility to replace equipment later.
The catch is that lease structures vary. End-of-term purchase rights differ by agreement, and payments don't automatically build toward ownership the way a loan payment does. Return conditions and additional charges can also affect the total cost, so reading the fine print before signing matters more here than with a straightforward loan.
Rent-to-Own for Eligible Trailers
C3 Rentals, a rent-to-own provider that works through trailer dealers, offers agreements on select new trailers, with terms from 12 to 48 months on trailers priced between $2,500 and $20,000. Prequalification runs on a soft credit check, so applicants can see whether they qualify without a hard pull on their credit.
Applicants must be 18 or older with a valid U.S. ID; no early-payoff penalties apply, and geographic restrictions limit where the program is available. Rent-to-own generally costs more than conventional financing but accepts lower credit scores.
This option functions as a backup rather than a first choice. It's designed for buyers whose conventional credit application was declined, not as a cost-saving alternative to a standard loan.
SBA-Backed Financing
The SBA 7(a) program can support equipment purchases and working capital, with loans made through participating lenders rather than the SBA directly. Maximum loan size reaches $5 million, though actual approval still depends on business eligibility, creditworthiness, and repayment ability.
The SBA 504 program covers qualifying major fixed assets and long-term equipment with at least ten years of remaining useful life, but it doesn’t fund working capital or inventory. Many 504 lenders also treat trailers as rolling stock, which the program doesn’t cover.
Government backing reduces the lender’s risk, but the business still has to meet standard underwriting. An eligible, creditworthy business with a reasonable ability to repay is still required before SBA financing moves forward.

SBA loans generally require a personal guarantee from the business’s major owners, even with government backing in place.
How Do You Apply for Commercial Trailer Financing?
Commercial trailer financing applications generally collect three kinds of information: details about the business, its financial records, and the trailer being purchased. Most applications move through these steps:
-
Gather business formation documents, tax ID, and ownership details.
-
Pull together financial records, such as bank statements and tax returns.
-
Collect the seller's quote or invoice, including trailer year, make, model, VIN, and purchase price.
-
Confirm whether the trailer is new or used and document its intended commercial use.
-
Submit the application and compare written offers before signing.
Lenders look for evidence of stability and cash flow. There's no universal minimum credit score across the industry; approval depends on the lender's own underwriting and how well the business's financial documentation supports repayment capacity.
Move From Approval to Pickup Faster With Poplar Bluff Trailer

Poplar Bluff Trailer finances trailers through business credit, personal credit, or rent-to-own, all arranged at the dealership.
Financing a commercial trailer comes down to matching the route to the purchase price and the business’s credit profile. Getting that match wrong can mean a declined application, a higher total cost, or a loan cap that falls short of the trailer the job needs.
Poplar Bluff Trailer’s finance team handles business and personal applications in one place, so contractors can get pre-approved before picking out a unit. Once approved, buyers can move straight from paperwork to pickup without shopping around for a separate lender. Apply for financing today and see where your business stands before you visit.
Frequently Asked Questions (FAQs)
How fast can I get approved for trailer financing?
Approval speed depends on the lender and how complete the application is. Dealer-arranged programs with online preapproval, like Poplar Bluff Trailer's, can establish a budget before a buyer visits the lot, while SBA-backed financing and bank equipment loans typically take longer because they require more extensive documentation.
Which financing is best for a commercial trailer loan?
The best option depends on the trailer's price, the business's credit and cash flow, and whether ownership is the goal. Dealer-arranged financing suits straightforward single-trailer purchases, while equipment loans or SBA loans fit larger transactions requiring independent loan comparison.
Do I need a down payment to finance a trailer?
Down payment requirements depend on the lender and the applicant's credit approval rather than a fixed industry standard. Some dealer-arranged programs may require less upfront cash than a direct equipment loan, depending on the lender's terms.
Is rent-to-own a good option for a business buying a trailer?
It can be, especially for a business with limited credit history. C3 Rentals accepts businesses as well as individual applicants, but rent-to-own trailers aren’t offered at the listed cash price, so the total cost runs higher than with a standard business loan.
What financing options does Poplar Bluff Trailer offer?
Poplar Bluff Trailer offers three routes: business financing based on company credit, personal credit financing for owner-operators, and rent-to-own through C3 Rentals on eligible new trailers. Buyers can start an application directly from any trailer’s listing on the website.
*Note: Prices shown are estimates based on current market conditions at the time of writing and may change without notice. Confirm trailer availability, specifications, and final pricing directly with Poplar Bluff Trailer.